Selling a Manufacturing Business in BC
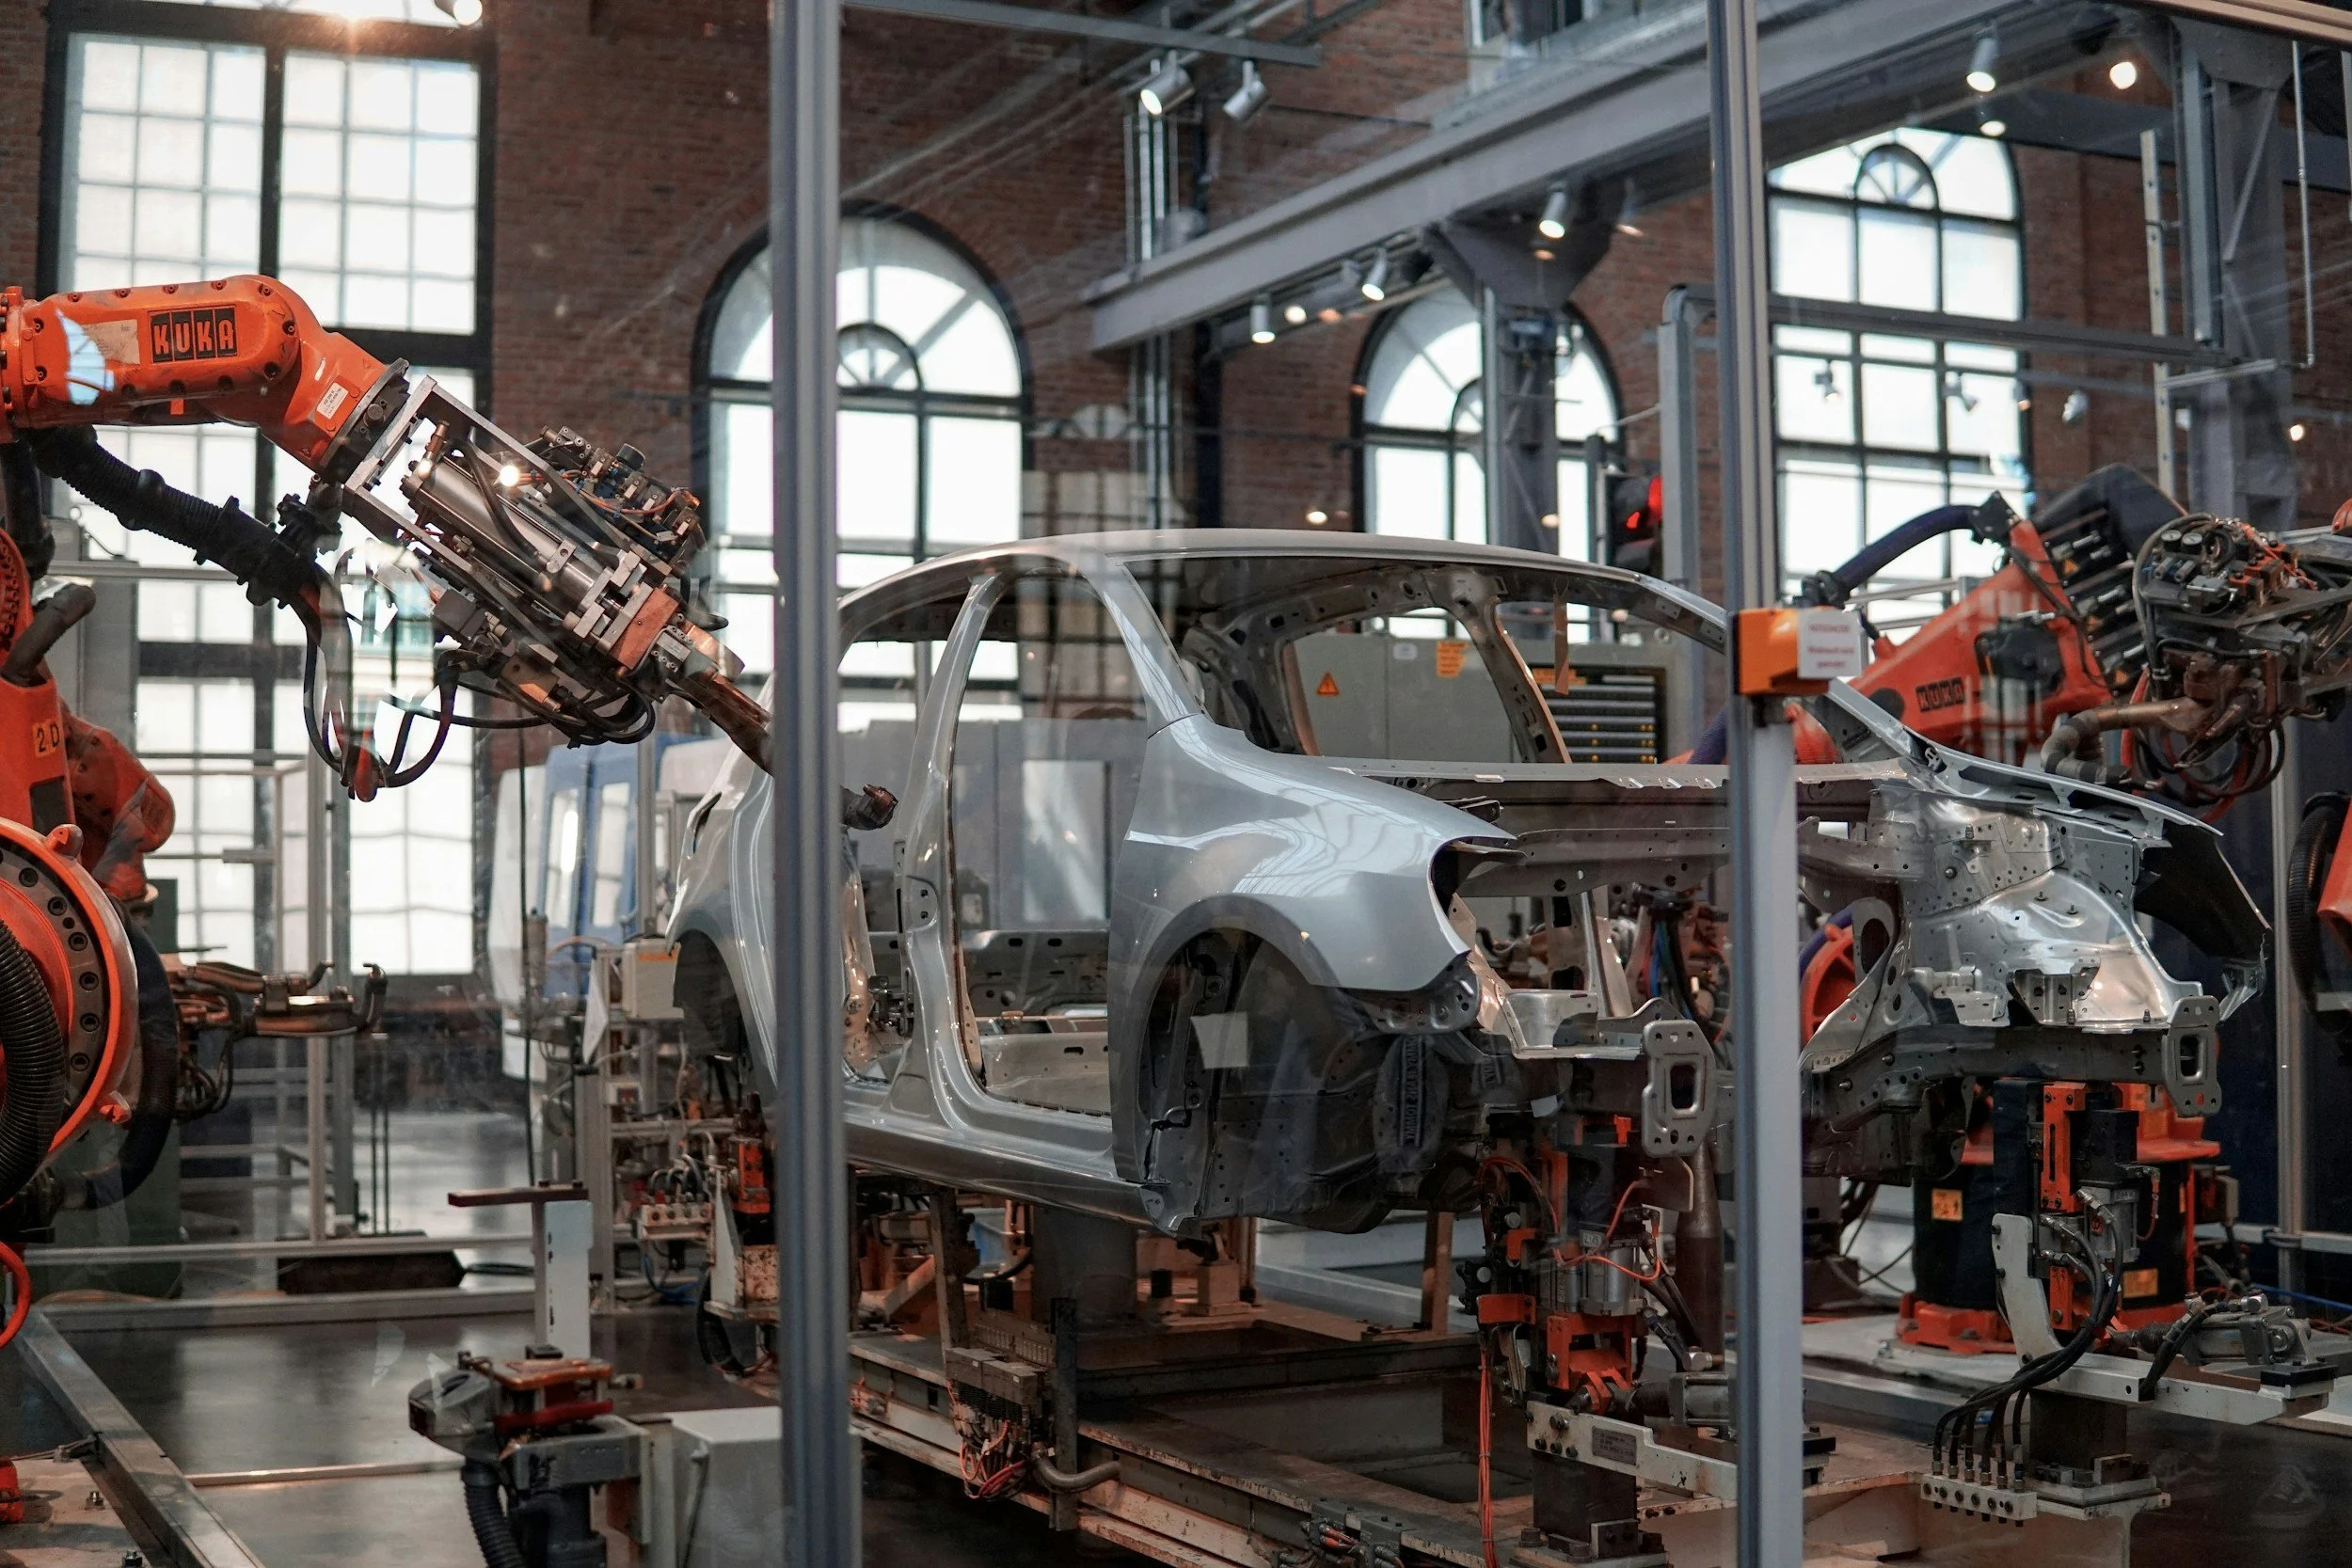
Selling a manufacturing business in BC is rarely a simple multiple-of-EBITDA exercise. The buyer is purchasing earnings, but also production capacity, customer approvals, equipment condition, labour depth, quality systems and a supply chain that may cross the Canada-US border. A weakness in any one of those areas can change both price and deal structure.
The strongest outcomes come from treating the sale as an industrial diligence exercise before it becomes a marketing exercise. Owners who can explain normalized earnings, maintenance capital expenditure, customer concentration and unused capacity give buyers fewer reasons to discount the business. That preparation also determines whether the right process is a broad M&A process, a targeted strategic sale or a family or management transition.
Manufacturing buyers purchase a production system
A manufacturer is more than its income statement. A buyer needs to understand how an order becomes a finished product, where constraints occur and which people, machines, certifications and suppliers make the system work. Two companies with the same EBITDA can have very different values if one has documented processes and available capacity while the other depends on the owner and several aging machines.
That is why the first preparation step is operational mapping. Document the production flow, capacity by work centre, historical utilization, scrap and rework, delivery performance, supplier dependencies and the roles of key employees. The objective is not a glossy presentation. It is a defensible explanation of what the buyer is acquiring and what investment will be required after closing.
Subsector economics shape the buyer universe
BC manufacturing includes food processing, specialty fabrication, plastics, packaging, value-added wood products, industrial equipment, electronics and aerospace-related operations. Each has different buyer logic. A food processor may attract brand owners, private-label producers and national consolidators. A precision fabricator may appeal to customers seeking vertical integration, US strategics seeking Canadian capacity and industrial platforms pursuing add-on acquisitions.
A generic buyer list misses those distinctions. The most valuable buyer is often not the largest company in the sector. It is the buyer that can use the seller’s certifications, customer approvals, geography or unused capacity to create value unavailable to a financial buyer. Understanding the difference between strategic and financial buyers helps an owner judge whether a premium is realistic or merely assumed.
Normalize EBITDA before discussing a multiple
Manufacturing financial statements commonly contain owner compensation, related-party rent, unusual repairs, foreign-exchange movements and discretionary spending that require normalization. The analysis must also separate temporary margin pressure from structural deterioration. A one-year decline caused by a plant move is different from a decline caused by a lost customer or obsolete product line.
Owners should reconcile every proposed adjustment to the general ledger and supporting documents. Buyers will test whether each item is genuinely non-recurring and whether an equivalent cost returns elsewhere. A credible normalization schedule supports value. An aggressive schedule creates distrust and can trigger a broader quality of earnings review.
The capital expenditure number buyers care about
Depreciation is an accounting allocation. Maintenance capital expenditure is the cash required to keep the plant competitive. The two numbers are rarely identical. A buyer will review equipment age, service history, utilization and the next major replacement cycle, then reduce the price or change the structure if near-term spending is higher than the seller’s historical depreciation.
Consider an illustrative manufacturer producing $1.4 million of normalized EBITDA. At a 5.0 times reference multiple, the initial enterprise value is $7.0 million. Diligence then identifies $1.2 million of equipment that must be replaced within two years, while normal annual maintenance capital expenditure is already reflected in earnings. If the buyer assigns $900,000 of present value to that near-term catch-up spending, the economic offer falls to $6.1 million. The headline multiple still sounds like 5.0 times, but the owner receives the equivalent of 4.36 times EBITDA. That $900,000 issue is more important than negotiating another quarter-turn on the multiple.
Customer concentration changes price and structure
Concentration is common in specialty manufacturing, particularly where an operation serves a small number of OEMs or national accounts. The percentage alone does not determine risk. Buyers examine contract duration, switching costs, qualification requirements, share of the customer’s spend, historical retention and whether relationships belong to the company or the owner.
A concentrated but deeply embedded supplier can be more defensible than a diversified manufacturer selling commoditized products. Even so, concentration often shifts consideration from cash at closing toward holdbacks, earnouts or seller financing. Owners should address the issue directly and connect it to the broader analysis of how customer concentration affects business value.
Working capital can move the closing proceeds
Inventory, receivables, payables and customer deposits make the working capital calculation especially important in manufacturing transactions. Inventory must be separated between current, slow-moving and obsolete items. Standard costing, overhead absorption and cycle counts all become diligence topics. A business can report strong earnings while carrying inventory that a buyer will not accept at book value.
The purchase agreement normally requires a normalized level of working capital to remain in the business at closing. Owners should calculate the target early, using monthly balances and seasonality rather than a single year-end number. The mechanics are explained in our guide to working capital adjustments in M&A.
Certifications and approvals can be transferable value
Quality certifications, regulated-process approvals and customer-specific qualifications can take years to establish. They may narrow the buyer pool if a purchaser cannot retain them, but they can also create a meaningful barrier to entry. Sellers should assemble audit reports, corrective-action logs, renewal dates, customer approval records and the names of employees responsible for maintaining each system.
The critical question is transferability. Some certifications attach to the facility or operating system, while customer approvals may require notice, requalification or a change-of-control review. The sale timeline should allow for those steps without disclosing the transaction prematurely.
Real estate should be valued separately
Many manufacturers own their facility through the operating company, a holding company or the shareholders personally. The decision to sell or retain the property affects the buyer universe, financing and after-tax proceeds. Buyers that want an asset-light acquisition may prefer a long-term lease. Other buyers may require control of a specialized facility that would be difficult to replace.
The operating company must be normalized to market rent whether the real estate is sold or retained. Otherwise, the EBITDA multiple and property value overlap. Environmental history also matters for older industrial sites. Owners should compare an operating-business sale, a combined business and property sale and a sale with leaseback before going to market.
Deal structure allocates manufacturing risk
A share sale may preserve contracts, permits and operating continuity, while an asset sale can allow the buyer to choose assets and liabilities. The commercial answer depends on customer consents, environmental exposure, tax attributes and the transferability of licences and certifications. Our comparison of an asset sale and a share sale explains the broader trade-offs.
Manufacturing deals also use holdbacks, earnouts and transition agreements to allocate specific risks. A buyer concerned about one concentrated customer may tie deferred consideration to that customer’s revenue. A seller should resist a structure that makes payment depend on factors controlled by the buyer after closing.
Preparation should begin before the market hears about a sale
The most valuable preparation is usually operational. Build management depth, document production and estimating processes, clean the inventory records, separate maintenance from growth capital expenditure and address expiring certifications. These steps make the business easier to diligence and easier to operate without the owner.
A practical preparation period often runs twelve to twenty-four months, but an owner can still improve the process in less time by prioritizing the issues buyers will quantify. Our guides to increasing business value and preparing a business for sale provide a useful starting framework.
The goal is evidence that production, customer service and financial reporting will continue after the founder leaves.
That evidence should include monthly production and margin reporting, named responsibility for key accounts, maintenance records and a documented close process. Buyers assign more credibility to systems they can inspect than to a seller’s assurance that the team already knows what to do.
Frequently asked questions
How are manufacturing businesses valued?
Buyers usually start with normalized EBITDA or cash flow, then assess capital expenditure, customer concentration, equipment condition, working capital and strategic fit. Asset value can provide additional support, but it does not replace an earnings analysis for a profitable operating company.
Should the factory be sold with the business?
Not automatically. Selling the property can maximize total proceeds and give the buyer control of a specialized site. Retaining it can create rental income and widen the buyer pool. Both alternatives should use market rent and be compared after tax.
Will a buyer pay for unused production capacity?
Only when the capacity is usable and connected to a credible growth case. Buyers will test whether demand, labour, tooling and working capital can support the additional output. Empty floor space by itself is not value.
How does old equipment affect a sale?
Aging equipment can reduce value through expected replacement spending, downtime risk and lower efficiency. Reliable maintenance records and a clear capital plan help distinguish well-maintained older equipment from deferred investment.
How long does a manufacturing sale take?
A well-prepared process commonly takes several months from preparation through closing. Cross-border diligence, environmental work, equipment appraisals or customer approval requirements can extend the timeline.
Next steps
Before approaching buyers, establish a defensible view of normalized earnings, capital requirements and the realistic buyer universe. KitsWest Capital combines business valuation with transaction execution, including experience supporting industrial businesses such as the firm’s industrial manufacturer financing engagement.
If you are considering a sale, responding to buyer interest or planning a family transition, contact KitsWest Capital for a confidential discussion.